Buying a property
Coverage bound and documented before closing, matched to your lender's requirements.
Commercial property
For owners of self-storage, hospitality, and other special-purpose property.
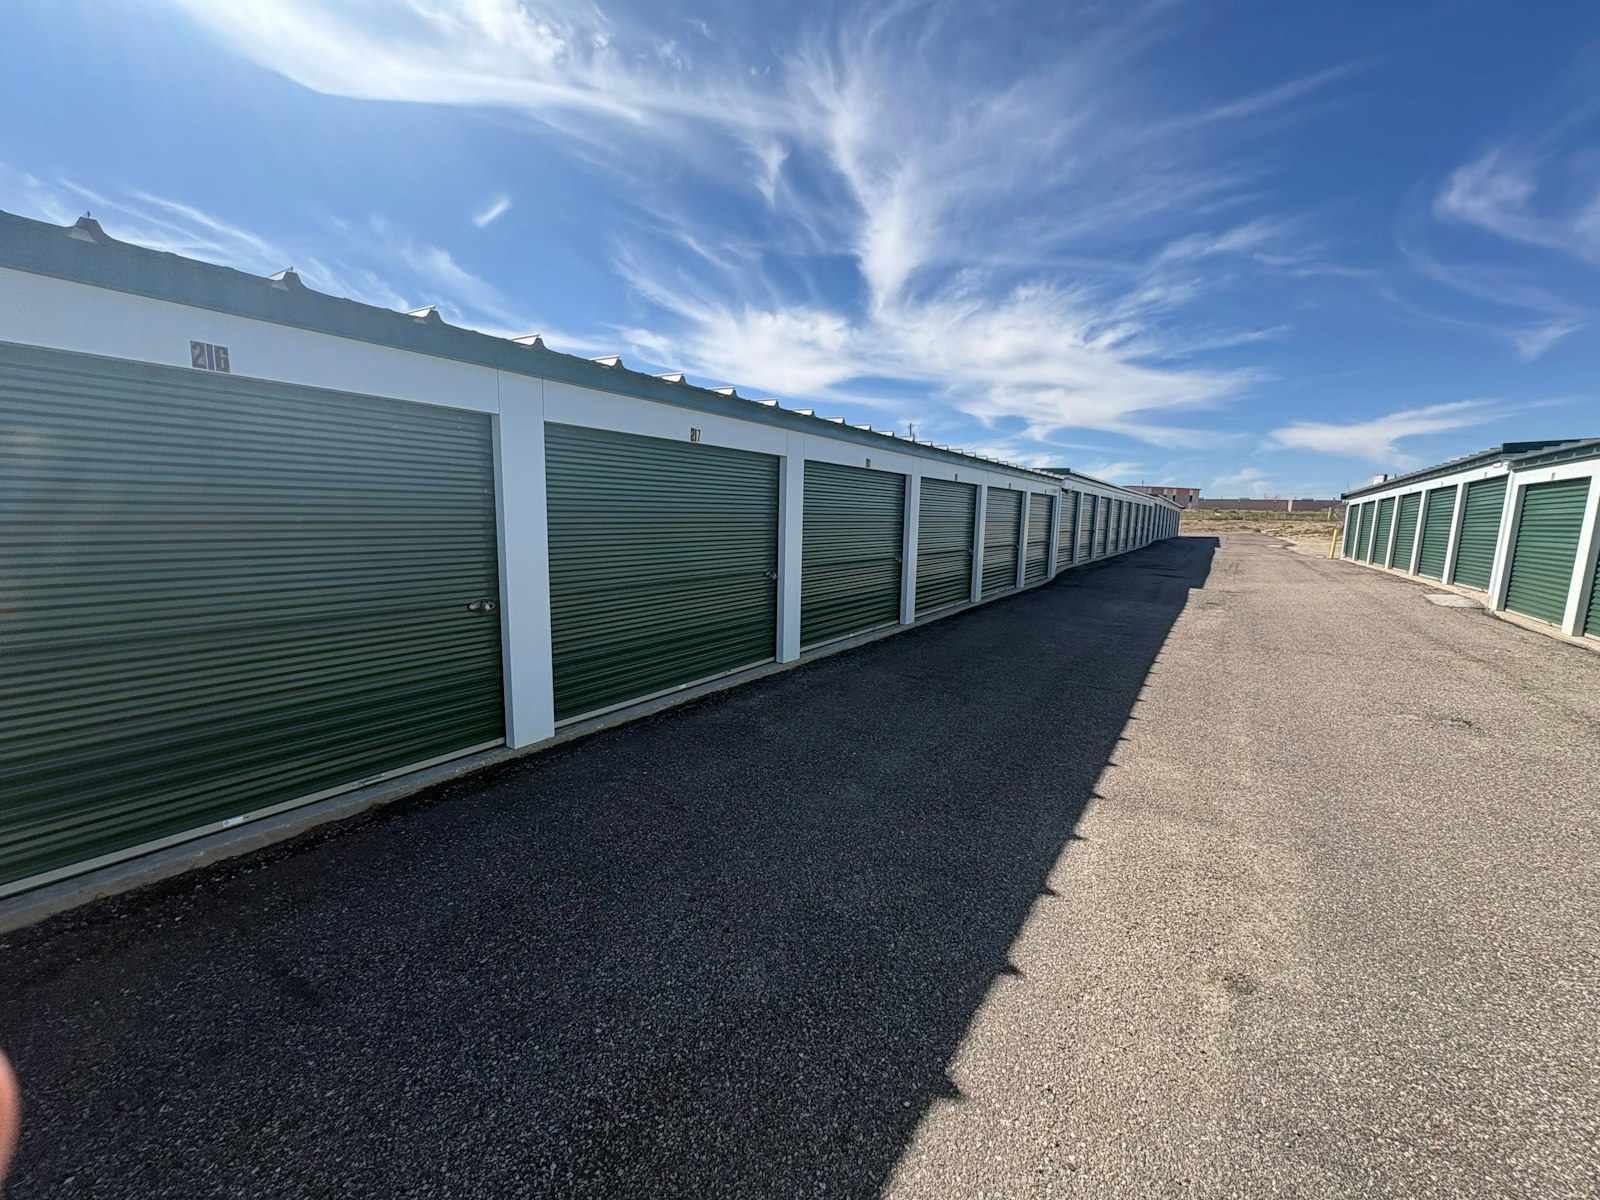
Some property doesn’t fit neatly into apartments, industrial, retail, or office. Self-storage, hotels and motels, and special-purpose buildings each come with their own questions.
With self-storage, insurers look at security, access control, and what customers are allowed to store. The owner insures the buildings and its liability, while customers are usually responsible for their own belongings. With hospitality, the operation matters as much as the building: who manages it, what services are offered, and how the property is maintained. Liability is a larger part of the picture.
Special-purpose property is often placed with insurers that focus on that use, sometimes through wholesale brokers and surplus lines insurers. We’ll explain what that means for your coverage before you decide.
Have something else? Ask us. Tell us what the property is and how it’s used, and we’ll tell you how it’s usually insured and what we’d need to take it to market.
What's needed varies by use. We'll tell you what applies to yours.
Having these ready makes a submission stronger.
Lenders usually ask for replacement cost on the buildings, business income for a set period, liability and umbrella limits, and the lender named as mortgagee and additional insured. Special-purpose property often comes with requirements specific to its use.
Coverage bound and documented before closing, matched to your lender's requirements.
A new lender means new requirements. We update your coverage and paperwork to match.
Builder's risk for the project, then a clean move to permanent coverage at completion.
Start early, see your options side by side, and avoid a gap.
Your current policies if you have them, a statement of values, five years of loss runs, and your lender's insurance requirements. Missing something? Start anyway.
Yes, when the standard market can't place a property. We'll explain what that means for your coverage before you decide.
From single buildings to multi-property portfolios, across apartments, industrial, retail, office, mixed-use, and specialty property.
Not yet. We're licensed in California today.
Tell us what's happening and when. Your broker will reply within one hour on business days.